

CreditWise from Capital One analysis by Appwee
When I want to keep an eye on my credit without turning it into a second job, I look for three things first: whether the app is genuinely free, whether the information is easy to understand, and whether it helps me notice a problem early rather than simply showing me a number. CreditWise from Capital One is built around that straightforward use case. It is a free finance app from Capital One Services, LLC that focuses on credit scores and monitoring, and I found it most useful as a calm, regular check-in rather than as a complete personal-finance command center.
The app is available to everyone in its age-rating category, runs on operating system version 11 or later, and has been available since April 12, 2016. Its current version is 1.150.0. With an average rating of 4.6 from around 116 thousand ratings and more than 5 million installs, it is clearly a familiar choice for people who want basic credit awareness on a phone. Still, popularity does not automatically make it the right tool for every borrower, so I would judge it by the job I needed it to do.
How I would decide whether CreditWise fits
The first question is whether I need monitoring or management. CreditWise is aimed at helping me follow my credit situation and spot changes. That is different from an app designed to manage a full household budget, pay bills, track investments, or organize every account in one place. If my main goal is to understand whether something has changed in my credit profile, the focused approach is helpful. If I want a complete financial dashboard, I would look elsewhere or use it alongside another service.
The second question is how often I will actually check it. A credit-monitoring app works best when it becomes a small habit: I open it periodically, review the current information, and investigate anything unexpected. It is not especially useful if I install it once, glance at the score, and never return. I also would not treat the displayed score as a permanent verdict on my financial health. Credit decisions can involve different information and criteria, so I use the app as an indicator and an early-warning tool, not as a promise about approval.
The third decision point is simplicity. I do not want a screen filled with financial products when all I am trying to do is answer, “Has anything changed?” CreditWise has a clear identity, which makes it easier to approach than a broad financial app with credit features buried among budgets, offers, and account tools. That focus is one of its strongest practical qualities.
A realistic everyday use
Imagine I am preparing to rent a new apartment or apply for a car loan. Before making the application, I open CreditWise to review my current credit picture and look for anything that seems unfamiliar. If I notice a change, I can pause and investigate instead of discovering the issue while completing an important application. Even when I am not applying for anything, a quick periodic check can help me notice a problem earlier than I would by waiting for a lender to mention it.
I also find this workflow useful after a major financial change. If I recently paid down a balance, opened an account, or finished dealing with an old obligation, I can use the app as one place to watch for movement over time. I would not expect every change to appear instantly or interpret every fluctuation as a crisis, but keeping a simple record of what I saw gives me better context than checking only when I am already under pressure.
What the focused design does well
The strongest part of CreditWise is its low barrier to entry. Because it is free, I do not have to decide whether a subscription is worth it before building a monitoring habit. That matters for someone who is new to credit, rebuilding after missed payments, or simply trying to become more organized without adding another monthly bill.
I also appreciate that a focused credit app can reduce distraction. In a general finance app, credit information may compete with spending charts, account balances, investment screens, and promotional material. Here, the reason for opening the app is much clearer. If your priority is credit awareness rather than full financial management, that narrow purpose is a real advantage.
Another useful insight is that the app can serve as a conversation starter. When I am helping someone understand credit, I would rather begin with a current, visible picture than with vague advice about being responsible. Reviewing a change together can lead to practical questions: Was a payment late? Did a balance rise? Is an unfamiliar item worth investigating? The app does not replace financial education, but it gives the discussion something concrete to examine.
How I use it without overreacting to the score
I try not to judge my entire financial position by one number. Instead, I look for direction, unexpected changes, and information that needs a closer look. A small movement is not automatically meaningful, while an unfamiliar account or activity deserves attention even if the score itself looks fine. This is an important habit because people often focus on improving a number and overlook the more serious question of whether the underlying information is accurate.
I would also avoid checking repeatedly throughout the day. That creates anxiety without producing better decisions. A regular review schedule is more useful: check after a significant account event, before an important credit application, and occasionally as part of normal financial maintenance. The app is most valuable when it supports that routine rather than encouraging constant score watching.
Where alternatives may fit better
CreditWise is not the best choice for every situation. If I want to see checking, savings, credit cards, loans, spending categories, and investments together, I would choose a broader personal-finance app. Those services are usually better for cash-flow planning and household budgeting because their central question is “Where is my money going?” CreditWise asks a narrower question about credit monitoring, so comparing the two only makes sense after identifying the job.
A lender’s own app may be more useful when I need to manage a specific account. A bank or card application can be the better place for payments, statements, transaction details, account controls, and product-specific support. I would not replace those tools with CreditWise. Instead, I see it as a separate layer for monitoring credit awareness, while the lender’s app remains the place to handle the account itself.
Someone who wants extensive educational material, debt payoff planning, or detailed simulations may also prefer a more specialized credit service. Those alternatives can be a better fit when the user needs a guided plan rather than a monitoring view. I would choose CreditWise when I want a simpler checkpoint and another service when I need a structured program for changing my finances.
There is also a trade-off for people who already use several Capital One tools. The app may feel convenient as part of that ecosystem, but convenience should not be confused with complete coverage. I would still compare the information with statements and other relevant records when making a serious decision. No single mobile screen should become the only source I trust for an important application or dispute.
Limitations I would keep in mind
The focused design can feel limited if I expect a full financial workspace. I cannot use a credit-monitoring app as a substitute for a budget, a payment calendar, or a detailed debt strategy. That is not a failure of its intended purpose, but it is a reason to avoid installing it with unrealistic expectations.
There is also a learning curve around interpretation. Seeing a score is easy; understanding why it changed, how a lender may view it, and what action is appropriate requires more context. I would not make a rushed borrowing decision simply because the number moved. The responsible workflow is to examine the surrounding information, verify anything unfamiliar, and use official account channels when a correction or account action is needed.
Privacy and trust matter more to me in a finance app than visual polish. Before using any credit-monitoring service, I would review its current permissions and privacy information directly in the app and store listing, then use a strong device lock. I would also avoid checking sensitive financial information on a shared or unsecured device. These are practical precautions, especially because the app deals with information that can affect major decisions.
The cost of switching from another finance app
Moving to CreditWise is relatively easy when the goal is simply to add a dedicated credit check to an existing routine. Since the app is free, the financial cost of trying it is low. The real switching cost is organizational: I need to decide which app I will use for which task, remember where the authoritative account details live, and avoid comparing numbers without understanding why they may differ.
If I currently use a broad finance app, I would not delete it immediately. I would keep it for budgeting and account aggregation, then use CreditWise for its credit-focused view. After a few review cycles, I could decide whether the extra app reduces confusion or creates duplication. This trial approach is better than moving everything at once, especially when I rely on the existing service for bill reminders or transaction history.
If I am switching from another credit-monitoring service, I would compare the experience rather than chasing a single score. I would ask whether CreditWise makes changes easier to notice, whether its explanations are understandable, and whether I can build a review habit without paying. I would also keep any personal notes from the old service, such as dates when I checked an account or noticed a change, because the app itself should not be expected to replace my own financial recordkeeping.
One non-obvious benefit of this gradual approach is that it separates monitoring from action. I can use CreditWise to notice something, then go directly to the relevant lender or official account source to confirm and address it. That reduces the risk of treating a monitoring screen as the place where every financial problem must be solved.
Who should use it, and who should skip it
I would recommend CreditWise to a new borrower who wants a simple way to become more aware of credit, to someone rebuilding credit who wants a regular checkpoint, and to an organized user who already has separate tools for banking and budgeting. It also makes sense for a person preparing for a major application who wants to review their credit picture before starting the process.
I would be less enthusiastic for someone who wants one app to run an entire financial life. That user will probably be happier with a comprehensive money-management service, possibly keeping a credit-monitoring app only as a supplement. I would also suggest caution for anyone likely to become anxious over every score movement. In that case, a planned review schedule and basic credit education are more important than installing another notification-driven service.
People who need to make an urgent correction should not wait for an app to solve the issue. CreditWise can help identify a concern, but the next step may involve contacting a lender, reviewing account records, or following the appropriate dispute process. I see the app as a useful signal, not a replacement for official support or careful documentation.
My recommendation after using it as a decision tool
CreditWise earns my recommendation for a specific reason: it makes free credit monitoring approachable without pretending to be a complete financial manager. The app’s 4.6 average from roughly 116 thousand ratings and its base of over 5 million installs suggest that many people find this focused approach useful, and I understand why. It is easy to position in a personal routine, especially when I want awareness without another paid commitment.
My recommendation comes with clear boundaries. I would pair it with the apps or websites I use for payments, statements, budgeting, and account support. I would review it periodically, investigate unexpected information through official channels, and avoid treating the score as a guarantee of any future credit decision. That combination gives the app a sensible role instead of asking it to do work it was not designed to handle.
For me, the deciding advantage is not a flashy feature; it is the reduction of friction between wondering about my credit and actually checking it. The main drawback is equally clear: users seeking deep financial planning will outgrow its narrow scope. If your need is a free, focused credit check from Capital One Services, LLC, I think it is worth trying. If your need is complete money management, choose a broader alternative and treat this app, at most, as one part of that larger system.
Gallery
CreditWise from Capital One Pros and Cons
- Free credit score tracking with no credit card required.
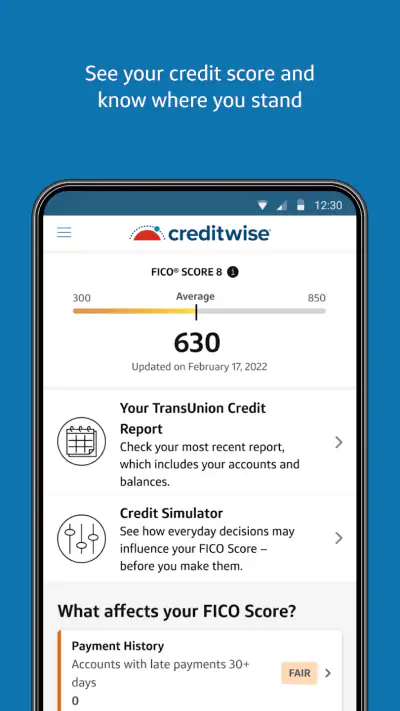
- Uses VantageScore 3.0 from TransUnion for regular score updates.
- Provides dark web monitoring and alerts for exposed personal information.
- Offers a simulator to show how financial actions may affect your score.
- Clean interface makes credit information easy for beginners to understand.
- The displayed score may differ from scores used by lenders.
- Features are mainly educational and do not repair credit directly.
- Some monitoring tools may require sharing sensitive personal details.
- Credit alerts can be delayed compared with activity on your credit report.
- Availability and features may be limited to eligible U.S. users.
CreditWise from Capital One Frequently Asked Questions
What is CreditWise from Capital One, and what does it do?
CreditWise is a free credit-monitoring service from Capital One that helps users review their credit profile and understand factors that may affect their credit health. It typically provides access to a VantageScore 3.0 credit score, score-change notifications, credit report information, and educational tools. You do not need to be a Capital One banking or credit-card customer to use the service.
Is CreditWise free to download and use?
Yes. CreditWise is generally available at no cost, and using its credit-monitoring features does not require a paid subscription. The service is designed to provide educational credit information without charging users for routine access to their score and monitoring tools. However, standard mobile-data charges may apply, and users should review the current terms and privacy policy because features and eligibility can change over time.
Will checking my score in CreditWise hurt my credit?
No. Viewing your information through CreditWise is considered a soft inquiry and should not lower your credit score. The app is intended for personal monitoring, so checking your score or credit report details regularly should not have the same effect as applying for a loan or credit card. A lender may perform a separate hard inquiry when you submit a credit application.
How accurate is the credit score and report information shown in CreditWise?
CreditWise provides useful monitoring information, but its score may differ from the score a lender uses. The service commonly displays a VantageScore 3.0 based on data from TransUnion, while many lenders use different scoring models, reporting agencies, or updated information. CreditWise can help you identify changes and possible errors, but it should not be treated as a guarantee of approval or as your only source of credit information.
What should I do if I find an error or suspicious activity in CreditWise?
If CreditWise shows incorrect personal or account information, review the details carefully and follow the available instructions for disputing information with the relevant credit bureau. For suspected identity theft, contact the credit bureaus, consider placing a fraud alert or credit freeze, and report unauthorized accounts promptly. CreditWise can help you notice changes, but it does not replace direct action with lenders, bureaus, or appropriate authorities.














